

North Admiral First-Time Buyers Close 13 Days Ahead of Their Contract Date
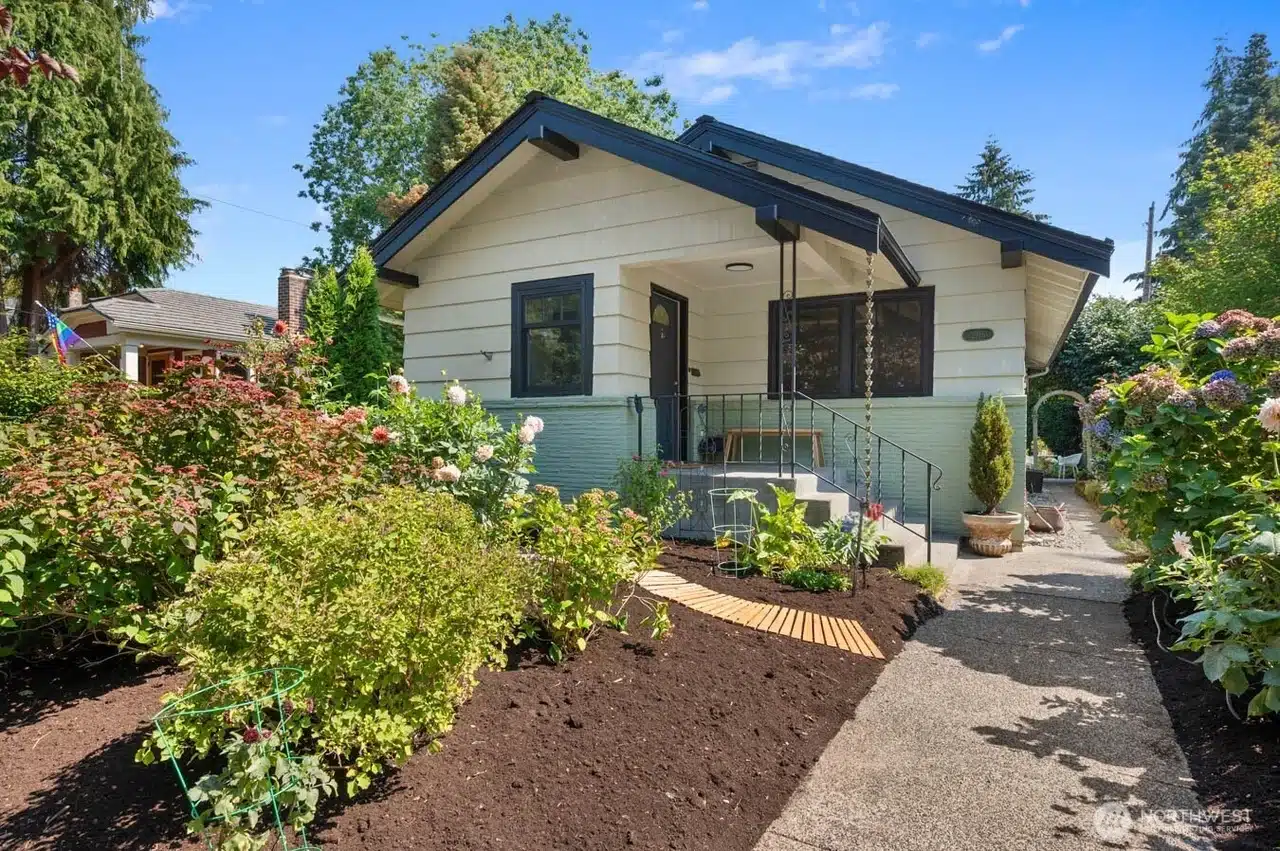
These first-time buyers were pre-approved in April 2025, lost out on an offer that August, and took a break from the search. When they came back in June 2026, they won their West Seattle home over competing offers, with a contract that called for an October 1 closing. They asked to close sooner, the seller agreed, and with a 6-day appraisal they closed on September 18, 16 days after mutual acceptance.
Loan Snapshot
The Situation
Keith first pre-approved these buyers in April 2025. That August they made an offer on a home, and it was not accepted. Instead of rushing into the next listing, they stepped back from the search for a while.
In June 2026 they started looking again. Because they already knew Keith and their file was familiar, getting their approval updated and ready to write an offer was quick. On September 2 they reached mutual acceptance on a home in North Admiral, beating other buyers in a multiple-offer situation.
Worth knowing: A declined offer is not the end of the road. Keeping your financing current while you take a break means you can move quickly when the right home comes up.
⚠️ The Challenge
During the loan, one of the buyers changed roles within the same parent company. Any change in employment has to be verified before closing, so the lender needed letters from the employer confirming the new role. With the letters in hand early, it never became a problem.
The purchase contract set the closing for October 1. The buyers wanted to get into their first home sooner, which meant the loan, appraisal and closing all had to be ready well ahead of schedule.
⚡ What Made It Work
- A relationship that started early: Keith had worked with these buyers since April 2025, so when they were ready again, nothing had to start from scratch.
- Ready to compete: with their approval already current, the buyers could write a strong offer quickly and win the home over other offers.
- The role change handled up front: the employer letters were requested and in the file before they could hold anything up.
- A 6-day appraisal with no rush fee: the appraisal came back quickly without the buyers paying extra to speed it up.
- An agreed earlier closing: the buyers asked to close before October 1, the seller agreed, and the file was ready to move.
The Outcome
The loan closed on September 18, 16 days after mutual acceptance and 13 days before the original contract date. More than a year after their first offer fell through, these buyers got the keys to their first home in North Admiral, and they were thrilled.

I love seeing buyers come back after a tough first round. Losing an offer is hard, and taking time off was the right call for them. When they were ready again, we picked up right where we left off.
Closing two weeks early takes everyone being prepared. The role change was a non-issue because we got the employer letters early, and a 6-day appraisal with no rush fee made the earlier date possible.
Can we close earlier than the closing date in our purchase contract?
Yes, if both buyer and seller agree. The change is made with an addendum to the purchase agreement, and the loan, appraisal, title and escrow all have to be ready for the new date. In this North Admiral purchase the contract called for an October 1 closing; the buyers asked to close sooner, the seller agreed, and the loan closed on September 18.
What happens if I change roles at my job while buying a home?
Tell your loan officer as soon as you know. A move to a new role with the same employer is usually straightforward: the lender verifies the new position and pay, often with a letter from the employer. That is how it was handled here, and it did not slow the closing down.
How long does a home appraisal take in Seattle?
It depends on how busy local appraisers are, and turn times can stretch when the market is busy. In this purchase the appraisal came back in 6 days without paying a rush fee, which helped the buyers close well ahead of schedule.
What should first-time buyers do if their offer isn’t accepted?
Take a breath and keep your financing ready. These buyers had an offer turned down in August 2025, stepped back from the search, and came back in June 2026. Because they already had a relationship with their loan officer, updating their approval was quick when they found the right home.
Ready to try again? Let’s get you prepared.
Keith keeps first-time buyers’ financing ready, so you can move fast when the right home comes up.
Mortgage Reel is powered by Fairway Independent Mortgage Corporation. NMLS #2289. Keith Akada, Loan Officer. NMLS #112443. Washington State Consumer Loan Company License MLO-112443. Loan details are real but buyer information is anonymized. Loan details reflect conditions at the time of closing and are not a guarantee of current pricing. All loans subject to credit approval. Equal Housing Opportunity.