

Maple Leaf Mortgage Guide
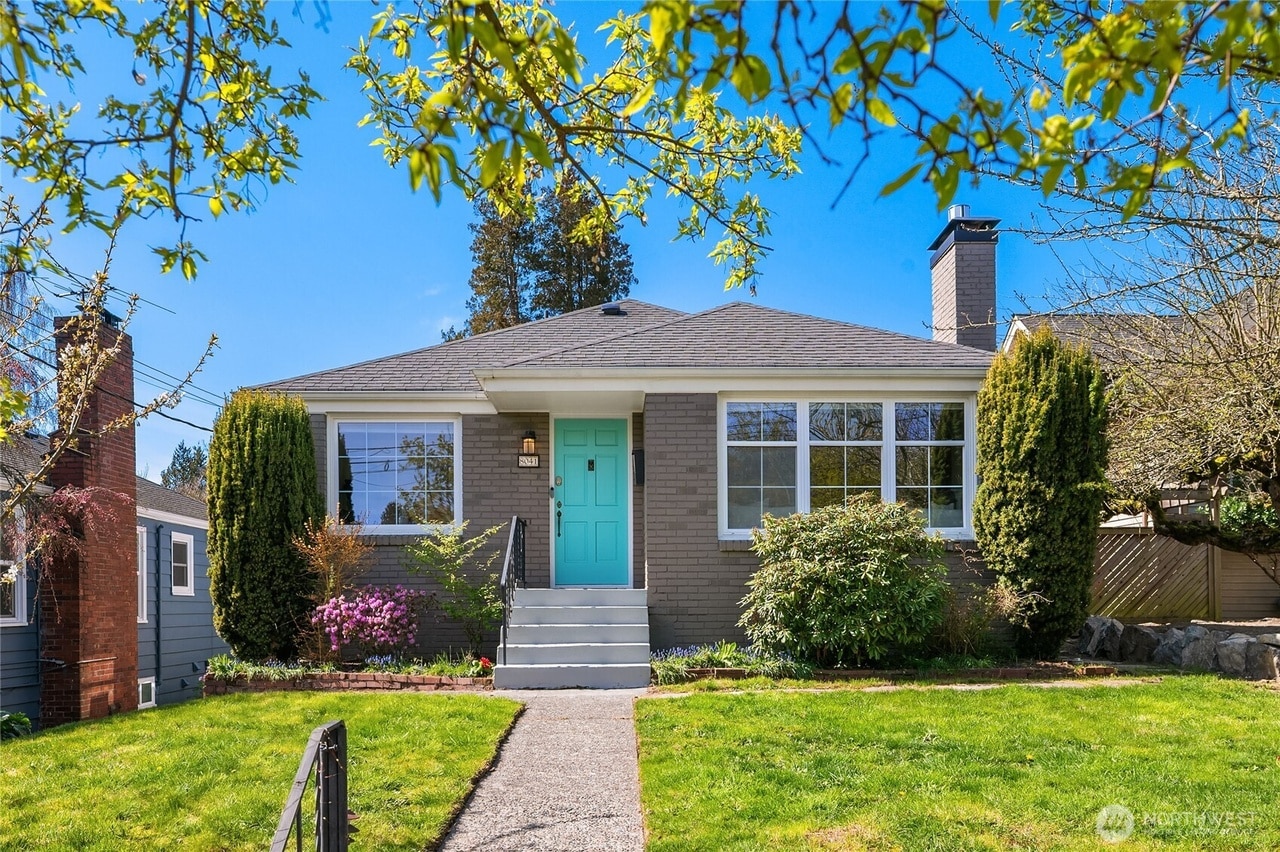
Maple Leaf combines tree-lined streets, Craftsman character, and a median around $800K with proximity to Northgate Light Rail and well-regarded northeast Seattle schools. Homes sell in a median of 14 days (Redfin, August 2026). Preparation is everything here.
Market Snapshot: Maple Leaf, Seattle
What buyers need to know about Maple Leaf
Maple Leaf runs roughly from NE 75th Street north to NE 105th Street, bounded by I-5 to the west and 35th Avenue NE to the east, a tightly defined residential neighborhood of about 9,400 residents in northeast Seattle. The housing stock is dominated by 1920s to 1950s Craftsman bungalows and mid-century ramblers, with newer infill townhomes appearing along the edges. Many of the classic homes retain their original character (hardwood floors, covered porches, mature gardens) while having been thoughtfully updated for modern living.
Market dynamics: According to Redfin, Maple Leaf scores 81 out of 100 on the Compete Score (August 2026), very competitive. Homes sell in a median of 14 days, and hot homes can go pending in around 5 days. Many homes receive multiple offers with waived contingencies. With a median around $800K, most purchases fall within conventional financing limits, but at the upper end of the range, particularly for larger homes on premium lots like this story’s $1.117M purchase, conventional financing still applies with 10% or more down. Arriving with a fully underwritten approval rather than a standard pre-qualification letter is the single biggest edge a buyer can have in Maple Leaf’s fast-moving market.
Schools: Seattle Public Schools serves Maple Leaf. John Rogers Elementary serves most neighborhood addresses for K to 5 and is well-regarded within the district. Eckstein Middle School serves 6th to 8th grade, one of Seattle’s largest and most academically active middle schools, with a broad range of extracurricular programs. Roosevelt High School serves Maple Leaf for 9th to 12th grade and is a well-regarded public high school, known for its strong arts program and academic achievement. School choice enrollment is available district-wide by application for families seeking specialized programs.
Sub-pockets and price distinctions: Maple Leaf is relatively uniform in character but varies meaningfully by location. The western and southern blocks, closest to Roosevelt and Northgate Light Rail stations, command slight premiums due to walkability and transit access, and tend to move faster. The eastern side of the neighborhood, while quieter and more residential, requires a car or bike to reach the train stations comfortably. Properties at the upper end of the price range (larger lots, view properties, or substantially renovated homes) can push well above the $1M median, as the client story below demonstrates. New infill construction along the neighborhood’s edges skews toward townhome buyers looking for modern finishes at accessible price points.
Transit and commute: Maple Leaf sits between two Link Light Rail stations: Roosevelt Station and Northgate Station, both approximately 1.5 miles from the neighborhood’s center. From Roosevelt, downtown Seattle is a 13 to 15 minute train ride; the University of Washington is 4 to 6 minutes. From Northgate, connections to Snohomish County via Community Transit are available. A dedicated neighborhood greenway connects Maple Leaf to Northgate Station for cyclists and pedestrians. For drivers, I-5 access puts downtown Seattle 15 to 25 minutes away depending on traffic. The honest caveat: walking from Maple Leaf’s eastern edge to either station is a 25 to 35 minute walk. Many residents drive or e-bike to the station, making car ownership still relevant in this neighborhood.
What tends to derail purchases here: Speed is the primary challenge: at a median of 14 days on market, buyers who aren’t fully prepared lose homes regularly. Beyond that, the upper end of Maple Leaf’s price range introduces conventional vs. jumbo structuring decisions that matter. Buyers at the $1M+ price point need to understand exactly where their loan amount lands relative to King County’s conforming limit of $1,063,750, because whether you need 10% or 20% down can depend on how you structure the loan. Keith navigates these decisions regularly for Maple Leaf buyers and can advise on the optimal structure before you make an offer.
What loans actually work here, and why
Conventional with 10% to 20% down is the dominant structure in Maple Leaf’s $650K to $975K range. With a median around $800K and King County’s conforming limit at $1,063,750, most Maple Leaf purchases stay within conventional territory, meaning no jumbo qualification requirements and access to standard pricing. Buyers with 10% down on an $800K purchase produce a $720K loan, well within conventional limits. The client story on this page, a $1.117M purchase with 10% down, required careful structuring to keep the $1,005,300 loan amount within conventional limits, which it did, narrowly.
Jumbo financing becomes necessary when loan amounts exceed $1,063,750. For Maple Leaf buyers targeting premium properties above $1.2M, or buyers with smaller down payments on upper-range homes, jumbo loans apply, typically requiring 10% to 20% down and stronger income documentation. At Maple Leaf’s price range, the conventional-to-jumbo threshold is a real planning consideration for buyers in the upper tier.
Relocation and new employment loans are more common in Maple Leaf than in many Seattle neighborhoods, driven by the neighborhood’s appeal to out-of-state buyers returning to Seattle or relocating for tech employment. As demonstrated in the client story below, new job start date timing, offer letter documentation, and loan structure are all critical to closing successfully when a buyer is starting a new position. Keith has closed multiple relocation loans in this neighborhood and understands the underwriting nuances well.
Getting a second opinion matters more than many buyers realize. The client story below involved a buyer who was already pre-approved by a national online lender, and saved on both rate and closing costs by comparing. Pre-approval from one lender is not a commitment. In Maple Leaf’s competitive market, arriving with the best possible financing terms (rate, cost, and credibility) can make the difference between winning and losing an offer.
Loan structures from buyers Keith has helped close in Maple Leaf
Real scenarios, anonymized but with actual numbers, strategies, and outcomes.
Buying in Maple Leaf?
Keith can walk you through a mortgage strategy built around your situation: conventional, jumbo, relocation. No pressure, just clarity.
Mortgage Reel is powered by Fairway Independent Mortgage Corporation. NMLS #2289. Keith Akada, Loan Officer. NMLS #112443. Washington State Consumer Loan Company License MLO-112443. Price ranges are approximate and based on recent sales data from Redfin, Zillow, and Homes.com as of 2026. This is not a commitment to lend. All loans subject to credit approval. Equal Housing Opportunity.