

From Out of State to Maple Leaf: How a Second Opinion Saved on Rate and Cost
A couple relocating to Seattle from out of state, buying by video tour and screen share, had already been pre-approved by a national online lender. The day after mutual acceptance, their agent connected them with Keith. One competitive quote later, they switched lenders, saved on both rate and closing costs, and closed in 30 days while navigating the added complexity of a new job start date.
Loan Snapshot
The Situation
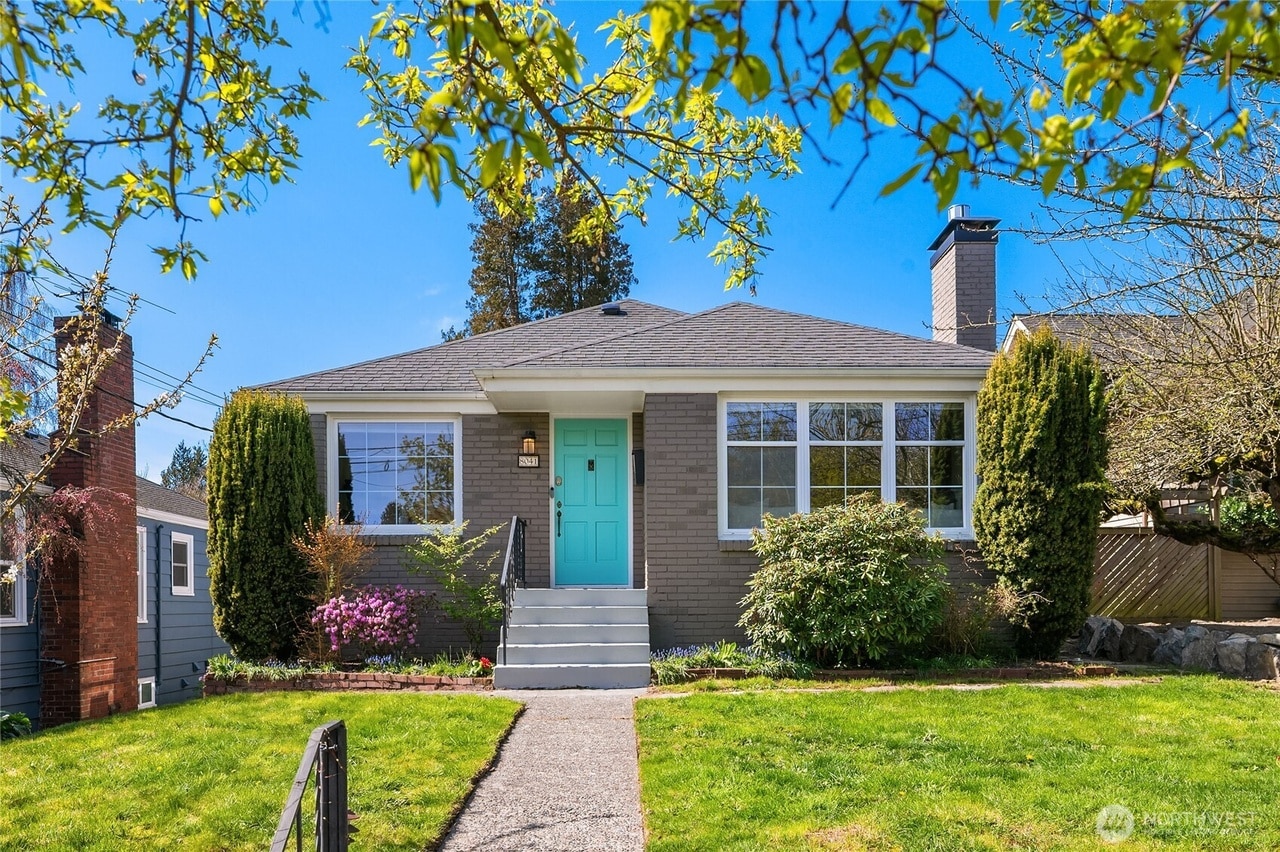
This couple was relocating to Seattle from out of state, coming home to be closer to family and starting fresh with a new job. They found their Maple Leaf home entirely by video tour and screen share, placing enormous trust in their real estate agent, Moose Math of The Moose Group at John L. Scott, who has deep experience guiding relocating buyers through Seattle’s market remotely.
They had been pre-approved by a national online lender before the process began. The day after mutual acceptance, they connected with Keith to ask about rate and fees, and that inquiry opened the door to a better deal.
What many buyers don’t know: Pre-approval from one lender does not obligate you to close with them. You can switch lenders after mutual acceptance, as long as there’s enough time to complete underwriting before closing. In this case, 30 days was enough.
Beyond the rate and cost comparison, there was a more complex underwriting challenge: the couple was starting a new job as part of their relocation. New employment during an active loan is one of the most common reasons closings fall apart: timing the job start date relative to the closing date, documenting the offer letter correctly, and structuring the loan to satisfy underwriting requirements were all critical details that required careful handling.
⚡ What Made It Work
- Competitive rate and closing costs: Keith beat the original lender’s quote on both rate and fees, saving the buyers real money at the closing table and over the life of the loan.
- New job structured correctly: relocating and starting a new job simultaneously introduces genuine underwriting risk. Keith structured the loan and timed the closing to satisfy lender requirements for new employment, a detail that could have caused a denial if handled incorrectly.
- Video tour purchase: buying a $1.117M home by video tour requires absolute confidence in your team. Moose’s experience with relocating buyers, combined with Keith’s clear communication throughout the loan process, gave the couple the certainty they needed to move forward remotely.
- 30-day close: despite switching lenders after mutual acceptance and navigating the new job complexity, the transaction closed on time in 30 days.
The Outcome
The couple closed on their Maple Leaf home in May 2026, welcomed back to Seattle, closer to family, in a neighborhood with tree-lined streets, strong appreciation, and easy access to the city. They paid less than their original lender quoted on both their rate and closing costs, and their new job start date was timed correctly to ensure a clean closing.
It started with a single question asked the day after mutual acceptance. That’s all it took.

Relocation loans have layers that most lenders don’t think about until it’s too late. Starting a new job is one of them. The job start date, the employment type, the offer letter language: these are all details that can make or break a closing. We got ahead of them early and structured everything correctly.
The other piece I want to highlight is the second opinion. This couple was already pre-approved. They had a lender. But they asked a question, and that question saved them money. I never pressure anyone to switch, but I always encourage buyers to compare. You owe it to yourself to know what’s available. Pre-approval is not a commitment.
And buying by video tour, that takes trust. Moose did an outstanding job keeping them confident through every step of the home search. When the right partner is in your corner, buying remotely works. This is proof of that.
Can I get a mortgage while relocating for a new job?
Yes, but the timing and structure of your loan must be handled carefully. Lenders need to verify income continuity, and starting a new job during the loan process introduces underwriting risk. The key factors are: start date relative to closing date, whether the new job is in the same field, whether you are salaried or hourly, and how the lender documents the offer letter. Keith has closed many relocation loans and knows exactly how to structure them for approval.
Is it worth getting a second opinion on my mortgage rate after pre-approval?
Absolutely. Pre-approval from one lender does not obligate you to close with them, and rates and fees vary significantly between lenders. In this Maple Leaf case, the buyers reached out to Keith the day after mutual acceptance, and he was able to offer a better rate and lower costs than their original pre-approval. Getting a second opinion costs nothing and can save thousands over the life of the loan.
What loan type is most common in Maple Leaf Seattle?
Conventional loans with 10% to 20% down are most common in Maple Leaf, where homes typically range from $650K to $975K. At the upper end, like this $1.117M purchase, conventional financing still applies as long as the loan amount stays within King County’s conforming limit of $1,063,750. In this case a 10% down payment produced a loan amount of $1,005,300, which required careful structuring to stay within conventional guidelines.
How does buying a home by video tour work with a mortgage?
Buying a home sight-unseen or by video tour is increasingly common for relocating buyers. From a mortgage standpoint, the loan process is identical: the appraisal is conducted in person by a licensed appraiser regardless of whether the buyers have physically toured the property. The key difference is that buyers must trust their agent and loan officer completely, as they are making a major financial decision remotely. Having experienced professionals on both sides is essential.

Relocating to Seattle? Let’s talk.
Keith has closed many relocation loans, including new job situations. Get a free second opinion on your current rate and fees.
Mortgage Reel is powered by Fairway Independent Mortgage Corporation. NMLS #2289. Keith Akada, Loan Officer. NMLS #112443. Washington State Consumer Loan Company License MLO-112443. Loan details are real but buyer information is anonymized. Loan details reflect conditions at the time of closing and are not a guarantee of current pricing. All loans subject to credit approval. Equal Housing Opportunity.