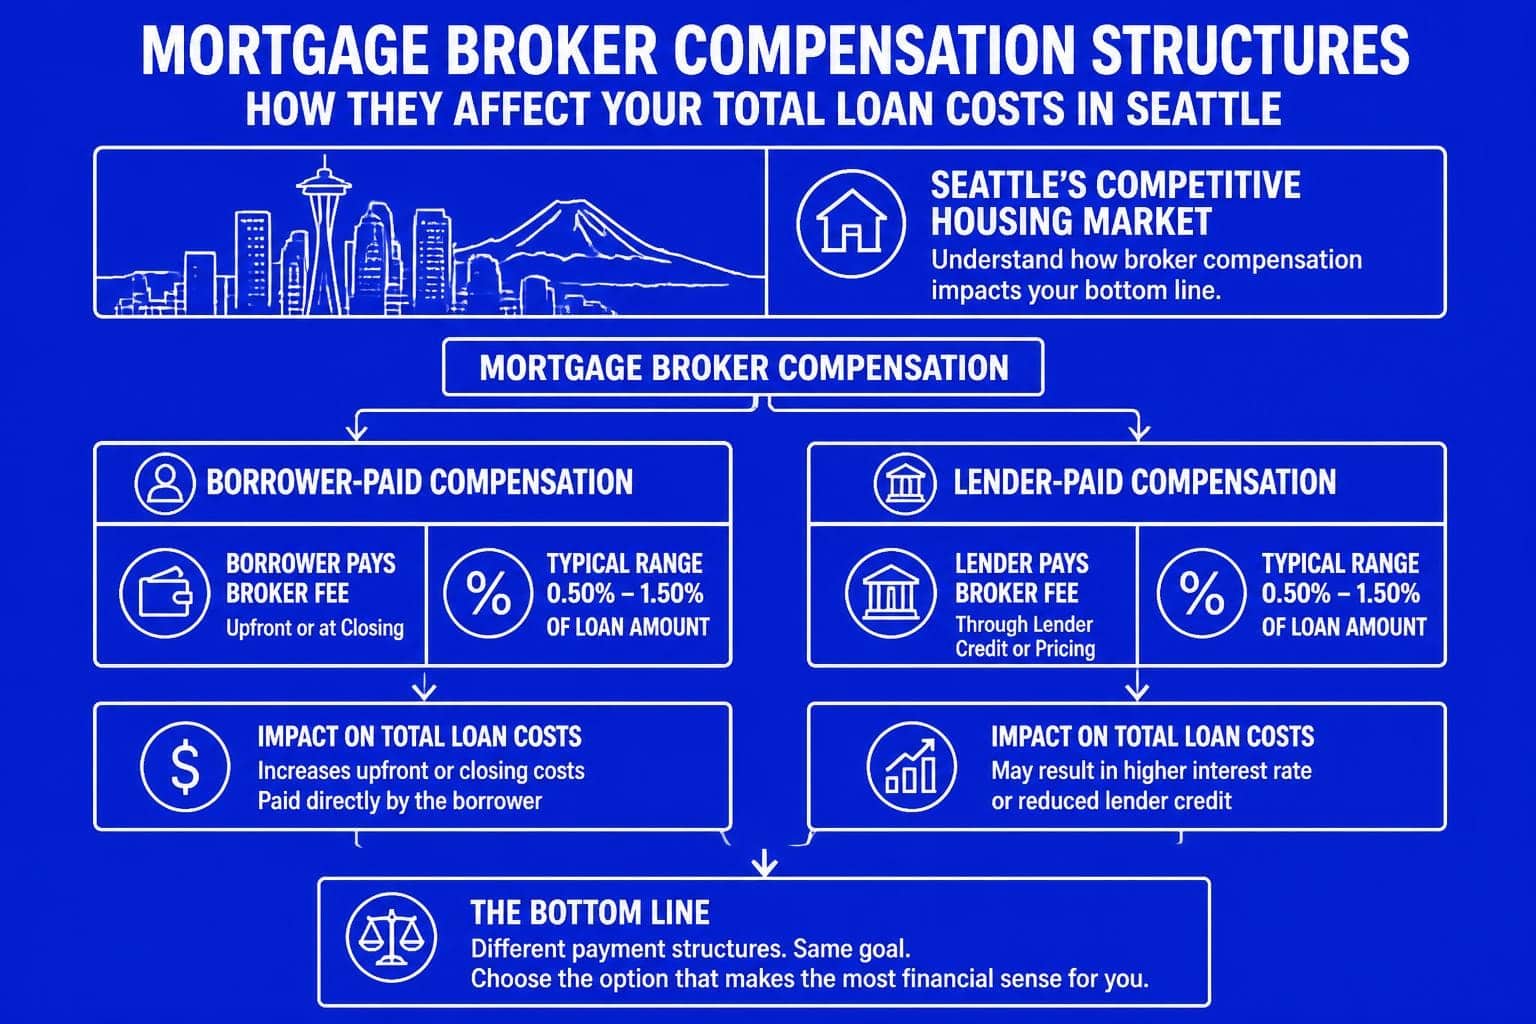
Mortgage broker charges are what you pay, directly or through your rate, for the person who arranges your loan. Under federal rules, a mortgage broker or loan officer is paid either by you or by the lender on a given loan, never both, and that pay cannot depend on your interest rate. Every charge appears in Section A, Origination Charges, of your Loan Estimate.
I have spent more than 25 years originating loans around Puget Sound, and the most useful thing I can tell you about fees is where to find them and how to compare them. Here is how mortgage originators get paid in 2026, and how to make sure you are comparing offers fairly.
Mortgage Broker vs Direct Lender: Who Gets Paid and How
A mortgage broker arranges your loan with an outside lender. The broker is paid either by you, as a disclosed broker fee, or by that lender, which builds the cost into the loan's pricing.
A direct lender, such as Fairway Independent Mortgage, where I am a loan officer, underwrites and funds the loan itself. The loan officer is paid by the lender, and any origination charges show up in Section A of your Loan Estimate like any other lender fee. Because the underwriting is in-house, a direct lender can often move faster, which is why my team can close in 9 business days.
Many Seattle buyers say “mortgage broker” for anyone who helps them get a loan. The label matters less than the numbers on your Loan Estimate, which is where every offer can be compared on the same terms.
The Federal Rules on Loan Originator Pay
Since 2014, the Consumer Financial Protection Bureau's loan originator compensation rules have set clear limits:
- No pay based on your rate or terms. A broker or loan officer cannot earn more by putting you in a higher rate or a riskier product. Pay can be based on the loan amount, but not on its terms.
- No double dipping. If you pay a broker directly, that broker cannot also be paid by the lender on the same loan.
- Anti-steering protections. An originator cannot steer you into a loan just because it pays them more, and should show you comparable options.
- Points and fees limits. For most loan sizes, Qualified Mortgage rules cap total points and fees at 3% of the loan amount.
You can read more in the CFPB's Owning a Home guide.
Where to Find Broker and Lender Charges on Your Loan Estimate
| Loan Estimate section | What it shows | Can you shop it? |
|---|---|---|
| A. Origination Charges | Lender fees, any broker fee, and discount points | Yes, by comparing lenders |
| B. Services You Cannot Shop For | Appraisal, credit report, flood certification | No, the lender chooses |
| C. Services You Can Shop For | Title and settlement services | Yes, from the provider list |
| Lender credits (Section J) | Money the lender contributes, usually in exchange for a higher rate | Compare along with the rate |
The fair way to compare two offers is to request Loan Estimates on the same day, for the same loan amount, loan type, and lock period, then compare Section A together with the interest rate and any lender credits. A low fee with a higher rate, or a low rate with points, can cost more or less depending on how long you keep the loan.
Points, Lender Credits, and the Trade-Off
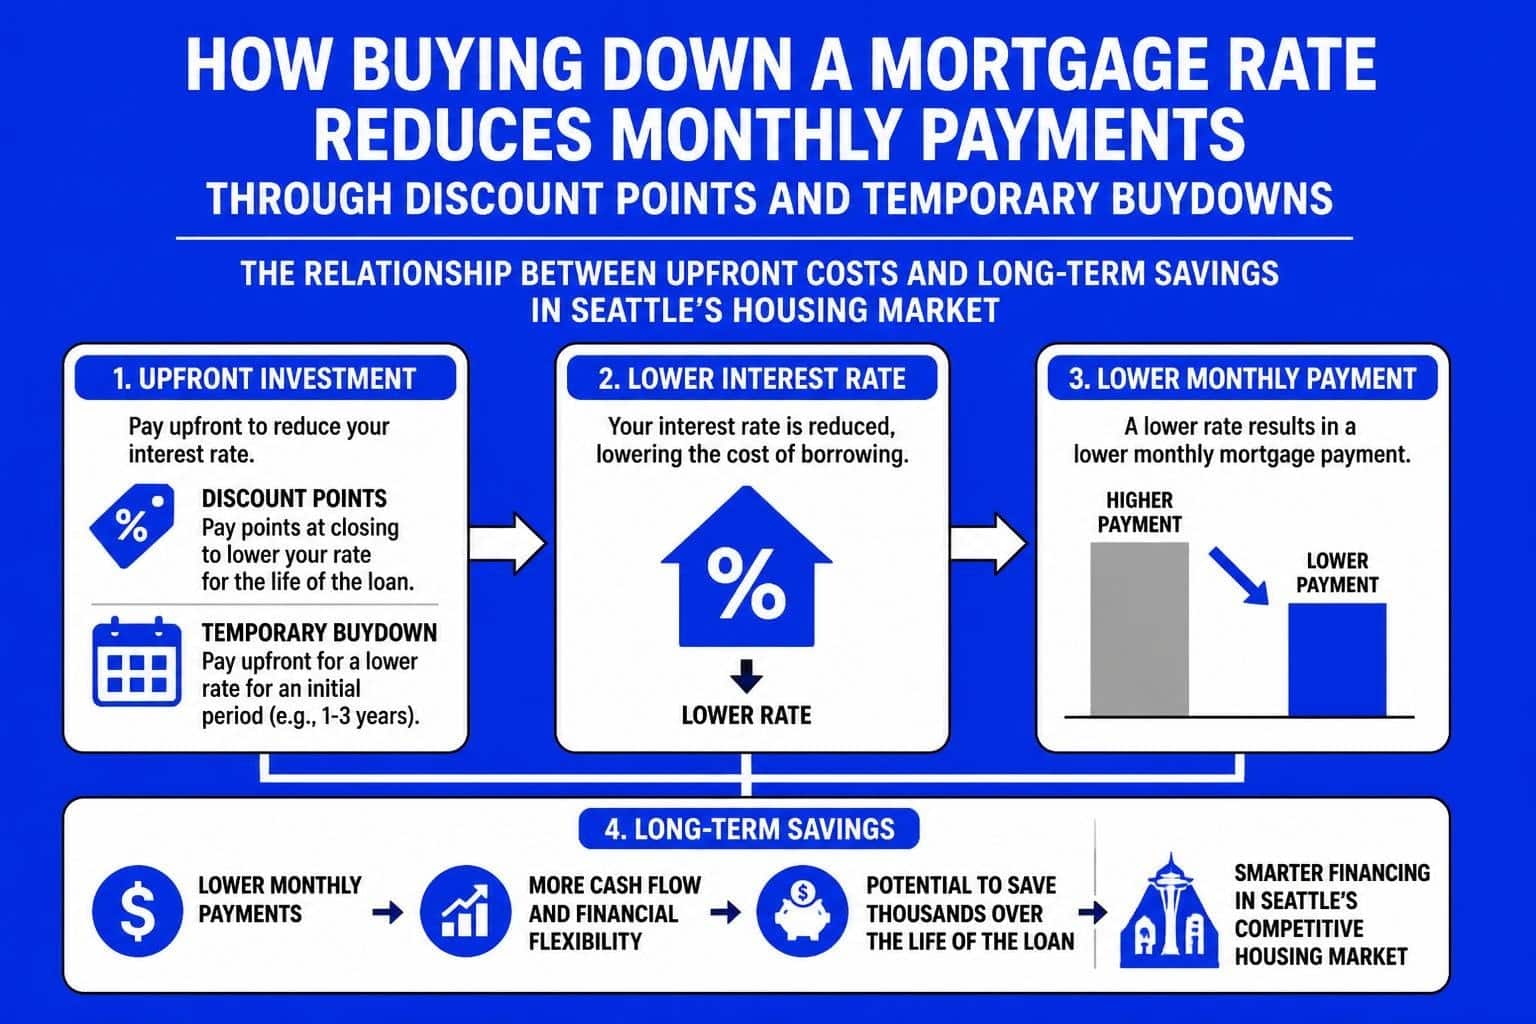
Discount points are optional fees you pay upfront to lower your rate; one point equals 1% of the loan amount. Lender credits work the other way, covering some closing costs in exchange for a higher rate. Points tend to make sense when you expect to keep the loan for many years. Credits can make sense when you are short on cash or expect to sell or refinance soon. I cover the math in buying down your mortgage rate.
Questions to Ask About Mortgage Fees
- Is anyone being paid a broker fee on this loan, and by whom?
- What is in Section A of my Loan Estimate, line by line?
- Are there discount points in this quote, and what would the rate be without them?
- Is there an application or processing fee before closing, and is it refundable?
- Can you show me the same loan with lender credits instead of points?
A loan officer who answers these clearly, in writing, is one you can trust with the rest of the process.
Red Flags
- Vague answers about how the originator is paid
- A quote that is not on an official Loan Estimate
- Pressure to sign before you have reviewed your Loan Estimate
- Large fees collected before closing without a clear explanation
Mortgage Costs Beyond the Originator
Origination charges are only part of your closing costs. In the Seattle area, buyers also pay for the appraisal, title and escrow, recording, and prepaid taxes and insurance, which typically add up to 2% to 4% of the price. Washington's real estate excise tax is paid by the seller, not the buyer. See my Seattle down payment guide and closing costs in Snohomish County for the full picture.
Mortgage Broker Charges: FAQs
How do mortgage brokers get paid?
A mortgage broker is paid either by you, as a disclosed fee, or by the lender, which builds the cost into the loan's pricing. Federal rules prohibit being paid by both on the same loan and prohibit pay that depends on your interest rate or loan terms.
Where do I see broker or lender fees?
In Section A, Origination Charges, of your Loan Estimate, which you receive within three business days of applying. It lists lender fees, any broker fee, and discount points, so you can compare offers line by line.
What is the difference between a mortgage broker and a direct lender?
A broker arranges your loan with an outside lender. A direct lender underwrites and funds the loan itself, and its loan officers are paid by the lender. In-house underwriting at a direct lender can make closings faster and more predictable.
Is there a limit on mortgage fees?
For most loan sizes, Qualified Mortgage rules cap total points and fees at 3% of the loan amount. Lenders also cannot raise most fees beyond what the Loan Estimate disclosed, except within set tolerances or after a valid change.
Are mortgage points tax deductible?
Points paid to buy a primary home are often deductible in the year paid if you itemize, while points on a refinance are usually deducted over the life of the loan. This is not tax advice, so check with a tax professional.
How do I compare mortgage offers fairly?
Get Loan Estimates on the same day for the same loan amount, loan type, and lock period, then compare the rate, Section A origination charges, points, and lender credits together. The lowest fee is not always the lowest total cost.
Let's connect. Call or text (206) 601-3426, email keith@mortgagereel.com, start your application, or book a time to talk. I will walk you through every line of your Loan Estimate, pressure-free.