The best first home buyer loans in Seattle depend on your savings, credit, and income. Conventional loans allow 3% down for qualified buyers, FHA 3.5% with scores as low as 580, and VA 0% for eligible veterans, and WSHFC down payment assistance can cover part of what is left.
Buying your first home in Seattle's competitive housing market requires more than just finding the right property. Understanding the best first home buyer loans available in 2026 can mean the difference between stretching your budget too thin and securing financing that positions you for long-term success. With rising home prices across Seattle, Bellevue, Redmond, and Kirkland, selecting the right loan program impacts not only your down payment and monthly payment but also your ability to compete effectively in multiple-offer situations.
Understanding First-Time Home Buyer Loan Options
The mortgage landscape offers several specialized programs designed specifically to help first-time buyers overcome common barriers like limited savings and shorter credit histories. The best first home buyer loans balance accessibility with competitive terms, allowing qualified applicants to purchase homes with smaller down payments while maintaining reasonable monthly costs.
What Qualifies as a First-Time Buyer
Most loan programs define a first-time home buyer as someone who hasn't owned a primary residence in the past three years. This definition is broader than many people realize, meaning you might qualify for first-time buyer programs even if you owned a home previously. Veterans may qualify for VA loans regardless of prior homeownership, and certain circumstances like divorce or being a displaced homemaker can also reset your first-time buyer status.
Understanding this definition matters because it opens doors to specialized financing options with reduced down payment requirements and more flexible credit standards. For tech professionals relocating to Seattle from other states, this three-year window can provide significant advantages when navigating the region's housing market.
Top Loan Programs for First-Time Buyers
Selecting from the best first home buyer loans requires understanding how each program aligns with your financial profile, employment situation, and homeownership goals. NerdWallet provides an overview of six first-time home buyer loans and programs that can help you compare your options comprehensively.
Conventional 97 and HomeReady Loans
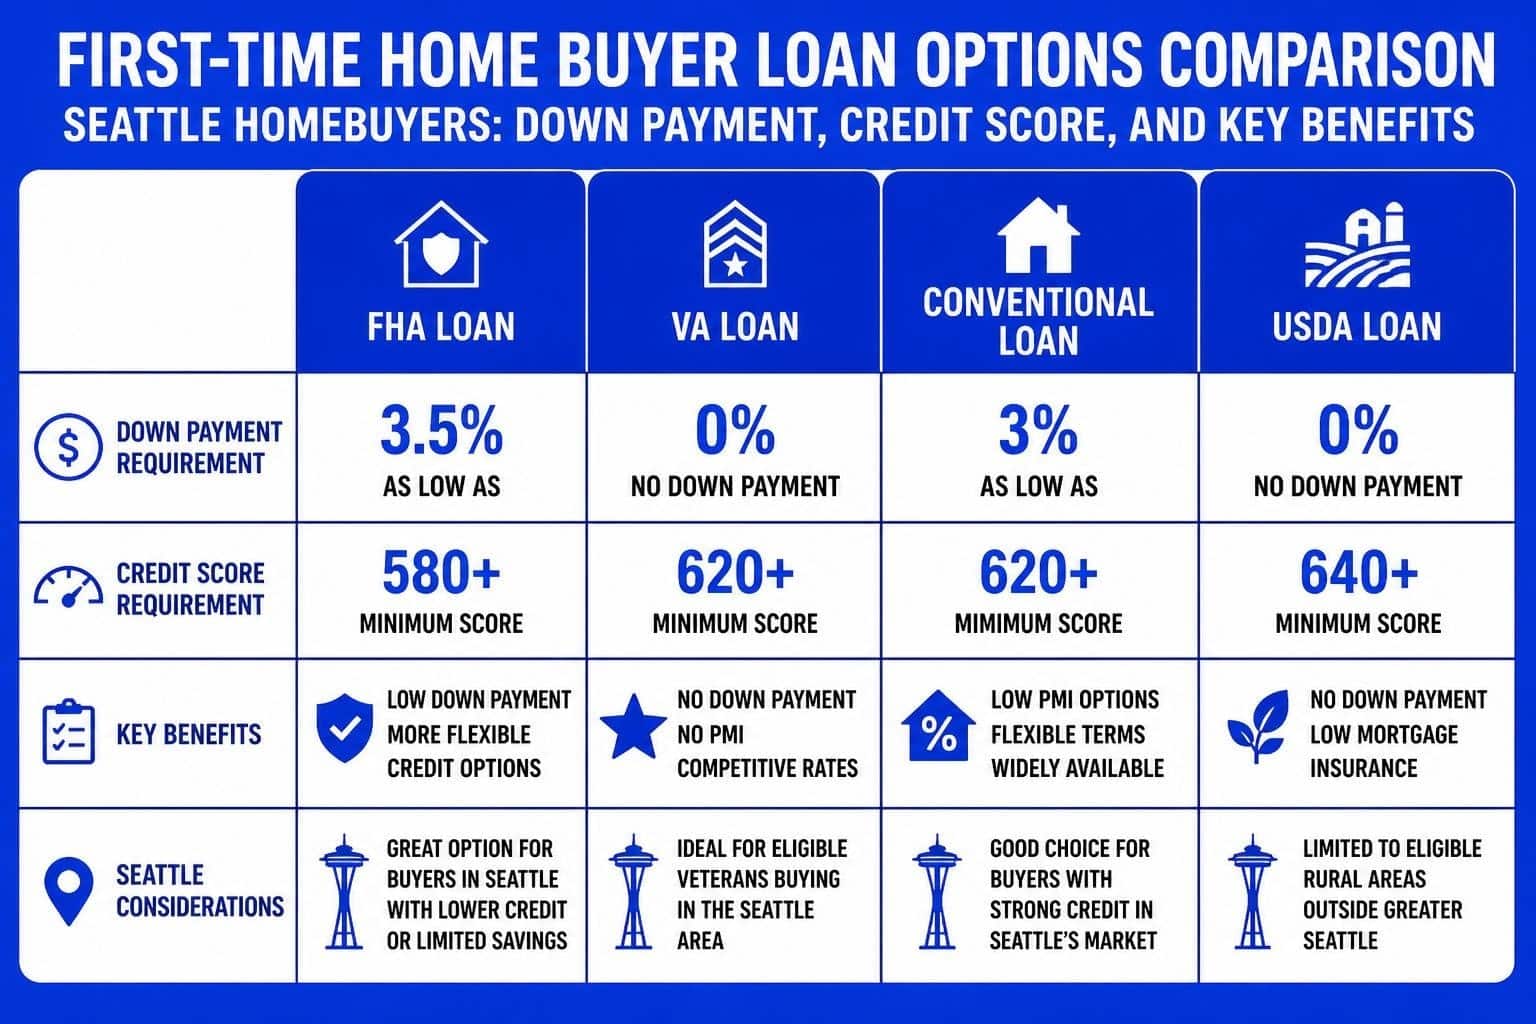
Conventional loans with as little as 3% down represent a powerful option for buyers with solid credit scores above 620 and stable employment history. These programs require private mortgage insurance (PMI) but offer competitive interest rates and greater property flexibility than government-backed alternatives.
Key advantages of conventional low-down-payment programs:
- Down payments as low as 3% of purchase price
- No upfront mortgage insurance premiums
- Cancellable PMI once you reach 20% equity
- Accepted by most sellers without concern
- Higher loan limits accommodating Seattle-area prices
The HomeReady program extends these benefits to buyers earning up to 80% of area median income, which is $120,960 in King and Snohomish counties for 2026, and it allows non-occupant co-borrowers, such as a parent, to strengthen the application. First-time buyers earning up to $181,440 (120% of area median income) may also qualify for Fannie Mae and Freddie Mac's waiver of certain upfront loan fees.
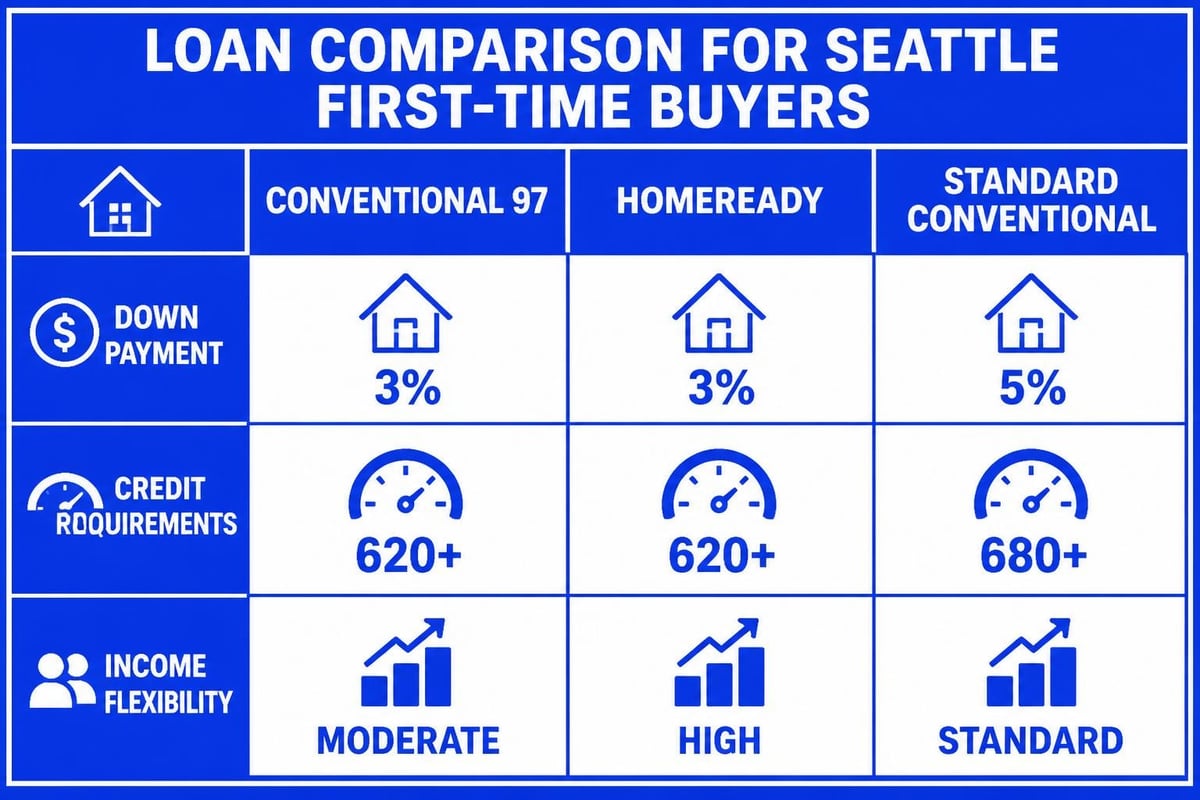
For buyers working with trusted mortgage lenders who understand stock-based compensation, conventional loans can qualify RSUs and vested equity as income, significantly expanding your buying power in competitive neighborhoods.
FHA Loans for Seattle First-Time Buyers
Federal Housing Administration loans remain among the best first home buyer loans for applicants with credit scores between 580 and 680 or limited down payment savings. With only 3.5% down required and more lenient debt-to-income ratios, FHA financing opens homeownership to a broader range of buyers throughout Seattle, Shoreline, and Lynnwood.
| Feature | FHA Loan | Conventional 3% Down |
|---|---|---|
| Minimum Down Payment | 3.5% | 3% |
| Minimum Credit Score | 580 (500 with 10% down) | 620 |
| Upfront Insurance | 1.75% of loan amount | None |
| Monthly Insurance | Required for loan term | Cancellable at 20% equity |
| Max Debt-to-Income | Up to 50% with compensating factors | Up to 50% through automated underwriting |
The trade-off with FHA loans involves mortgage insurance that remains for the life of the loan on most purchases, meaning you'll need to refinance to eliminate it once you build sufficient equity. However, for buyers prioritizing approval certainty and minimal upfront cash requirements, FHA programs deliver proven results.
Understanding how FHA financing works in Seattle’s market helps you determine whether the long-term insurance costs outweigh the near-term accessibility benefits. In neighborhoods like Lake Forest Park and Mill Creek where entry-level homes remain relatively affordable, FHA loans provide viable pathways to ownership.
VA Loans: Unmatched Benefits for Veterans
Service members, veterans, and eligible surviving spouses gain access to the most advantageous financing available through the Department of Veterans Affairs loan program. VA loans require no down payment, charge no monthly mortgage insurance, and typically offer lower interest rates than conventional alternatives.
VA loan advantages specific to Seattle-area buyers:
- Zero down payment, with no VA loan limit for borrowers who have full entitlement (the county limit only matters with partial entitlement)
- No monthly mortgage insurance reduces monthly payments significantly
- Competitive interest rates backed by government guarantees
- Lenient credit requirements with manual underwriting available
- Funding fee can be rolled into the loan amount
- No prepayment penalties
For veterans buying anywhere from Everett to Bellevue, this program removes the largest barrier to homeownership: down payment savings. The funding fee (2.15% for first-time use with less than 5% down) replaces monthly mortgage insurance and can be financed into the loan.
Veterans should explore VA loan options thoroughly to understand how certificate of eligibility, funding fee tiers, and entitlement work. For those with service-connected disabilities, the funding fee can be waived entirely, making VA financing even more advantageous.
USDA and State-Specific Programs
Beyond the mainstream options, specialized programs target specific geographic areas and income levels. USDA loans offer zero-down financing for eligible properties in designated rural areas, though most of King County doesn't qualify. However, certain properties in Snohomish County and outlying areas may meet USDA requirements.
Washington State Housing Finance Commission
The Washington State Housing Finance Commission administers several first-time buyer programs offering down payment assistance and reduced interest rates. These programs change annually based on funding availability and legislative priorities, making it essential to check current offerings when planning your purchase timeline.
WSHFC's Home Advantage pairs its first mortgage with down payment assistance of 3% to 5% of the loan amount at 0% interest. It is a deferred loan, not a grant, repaid when you sell, refinance, or pay off the first mortgage, and the household income cap is $215,000. House Key Opportunity and the City of Seattle (up to $76,000) serve lower incomes. I cover every program with 2026 limits in my 1st time home buyer programs guide.
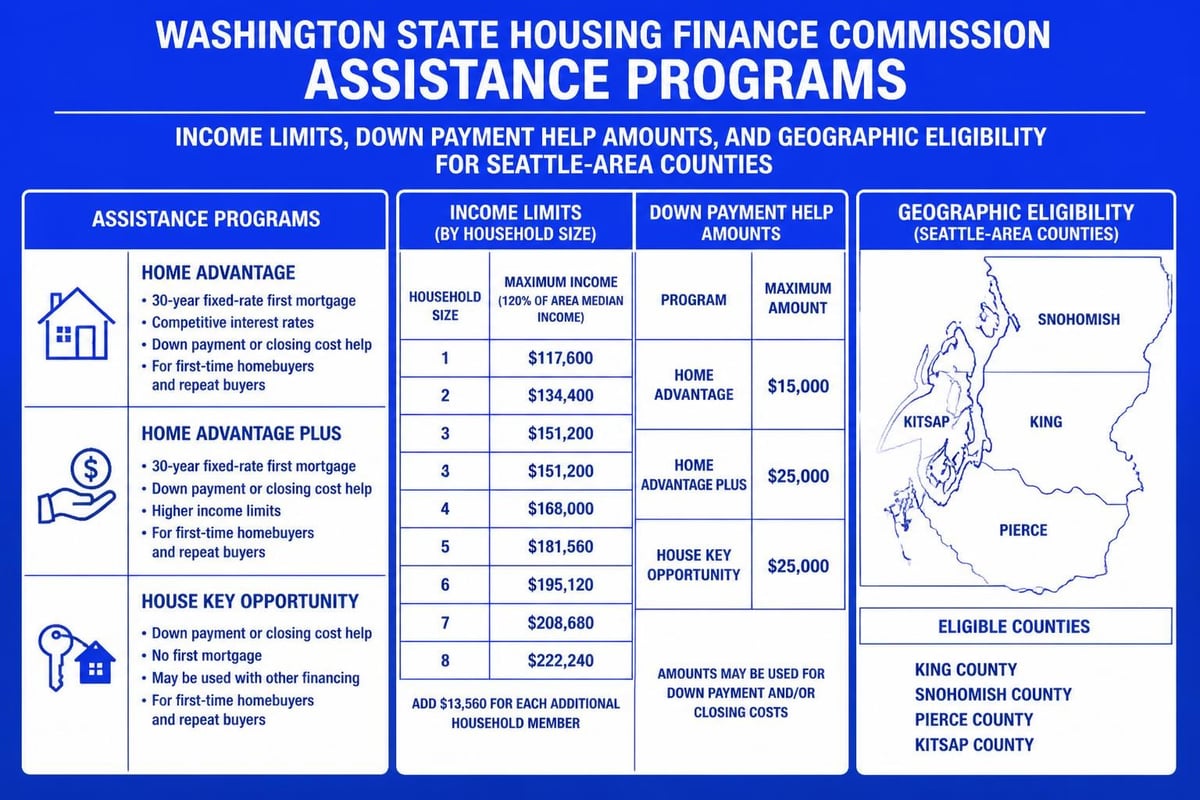
Working with experienced Seattle mortgage brokers who monitor state and local assistance programs ensures you don't overlook valuable resources that reduce your upfront costs significantly.
Qualifying Strategies for Tech Professionals
Seattle's concentration of technology employers creates unique opportunities and challenges for first-time buyers receiving substantial portions of compensation through stock grants, bonuses, and equity awards. The best first home buyer loans for tech workers accommodate these income sources through proper documentation and underwriting approaches.
Maximizing Buying Power with Stock Compensation
Amazon, Microsoft, and Google employees often have significant compensation in RSUs. Under Fannie Mae's current rules, vested RSU income can count once you have at least 12 months of time-based awards from your current employer, averaged over the last 24 months at the stock's 200-day moving average price. Unvested shares and sign-on grants do not count. See how RSUs impact mortgage approval.
Documentation requirements for stock-based income:
- Two years of W-2s showing stock income
- Recent pay stubs indicating vesting schedules
- Employer verification of future vesting
- Brokerage statements confirming holdings
- Explanation of any one-time bonuses or grants
This can substantially increase qualifying income compared to base salary alone. As an illustrative example, a software engineer earning $180,000 in base salary plus $120,000 in documented annual RSUs might qualify using $300,000 of income, about two-thirds more than the base alone. How much RSU income counts depends on your vesting history and schedule and is subject to underwriting.
Understanding jumbo loan qualification becomes essential when stock compensation pushes your target price range above conforming limits. Jumbo programs require stronger credit profiles and larger reserves but provide access to Seattle's most desirable neighborhoods.
Down Payment Sources and Strategies
Accumulating down payment funds represents the primary obstacle for most first-time buyers, particularly in a market as expensive as Greater Seattle. The best first home buyer loans minimize this barrier, but strategic planning accelerates your path to purchase.
Gift Funds and Family Assistance
All major loan programs permit gift funds from family members to cover down payment and closing costs. For a one-unit primary home, conventional loans allow the entire down payment to come from a gift at any down payment level (2- to 4-unit homes with less than 20% down need a 5% contribution from your own funds), and FHA and VA loans allow gifts as well.
Proper gift documentation includes a signed letter stating the funds are a gift with no repayment expectation, paper trail showing transfer from donor's account to yours, and sometimes documentation of the donor's ability to give. This process must be completed before closing to satisfy underwriting requirements.
For buyers receiving family assistance, understanding mortgage financing options that accommodate gifts while maintaining competitive rates proves essential to maximizing the benefit.
Retirement Account Withdrawals
First-time home buyers can withdraw up to $10,000 from traditional IRAs without the 10% early withdrawal penalty, though income taxes still apply. This is not tax advice, so talk to a tax professional first. Roth IRA contributions can be withdrawn tax and penalty-free at any time, while earnings follow the same $10,000 first-time buyer exception.
These strategies should be considered carefully against long-term retirement goals, but they provide legitimate down payment sources when other options fall short. Documenting retirement withdrawals requires statements showing the distribution and sourcing explanation for underwriters.
Comparing Loan Costs and Monthly Payments
Selecting the best first home buyer loans requires analyzing total costs beyond just the interest rate. Upfront fees, ongoing insurance requirements, and long-term payment trajectories all impact affordability and financial outcomes.
| Loan type | Minimum down | Upfront cost | Ongoing insurance or fee | Way out |
|---|---|---|---|---|
| Conventional 3% | 3% | No upfront mortgage insurance | PMI, cancellable | PMI ends at 78% of original value, or request at 80% |
| FHA 3.5% | 3.5% | 1.75% upfront premium, usually financed | 0.55% a year for most buyers, for the life of the loan if under 10% down | Refinance to conventional later |
| VA | 0% | 2.15% funding fee (first use, under 5% down); exempt with VA disability compensation | None | No mortgage insurance to remove |
| USDA | 0% | 1% upfront guarantee fee | 0.35% annual fee | Eligible rural addresses only |
Actual costs vary with your credit score, down payment, loan amount, and a full loan estimate, so I run these side by side for your situation. FHA, VA, and USDA figures come from HUD, VA.gov, and USDA Rural Development.
Redfin’s article discusses six types of first-time homebuyer loans with additional context on how each program performs in competitive markets, helping you align loan selection with offer strategy.
Credit Score Requirements and Improvement
Credit scores influence both loan approval and the interest rate you'll receive, making score optimization a valuable investment of time before applying. The best first home buyer loans remain accessible to those with scores above 620, but significant rate improvements occur as you move from good to excellent credit tiers.
Score Tiers and Rate Impacts
Conventional loan pricing adjusts by credit score band, with meaningful improvements at 680, 700, 720, and 740. Moving up even one band can lower your cost, and I can show you exactly how your score affects pricing on an actual Loan Estimate.
Rapid score improvement strategies:
- Pay down credit card balances below 10% of limits
- Become an authorized user on established accounts
- Correct any errors on credit reports immediately
- Avoid new credit inquiries during home search
- Keep all accounts current without exception
Even modest improvements from 660 to 700 can lower your cost over the life of the loan while improving approval odds. Starting this process 6-12 months before you plan to buy maximizes results and provides time for positive changes to fully reflect in your credit file.
Competitive Offer Strategies with Various Loans
Understanding how sellers and listing agents perceive different financing types helps you structure competitive offers even when using best first home buyer loans with lower down payments. In Seattle's market where multiple offers remain common, loan type perception influences seller decisions.
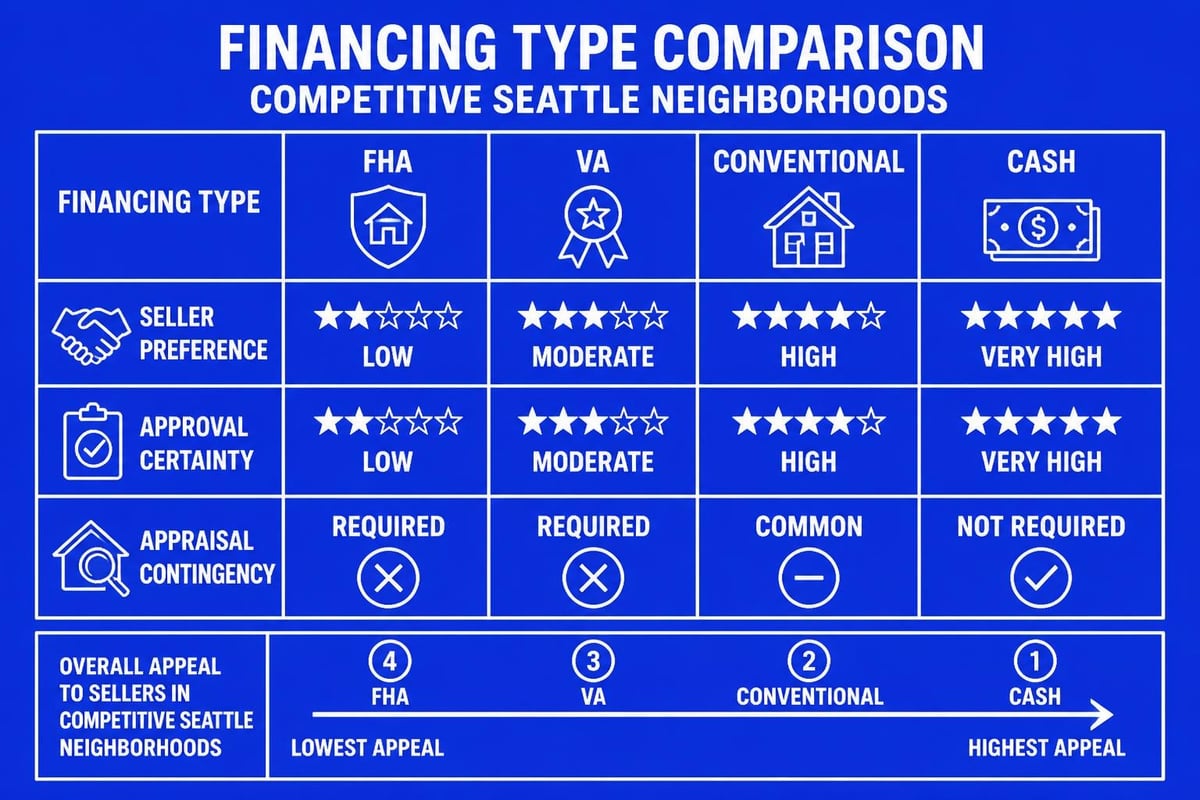
Overcoming Low Down Payment Concerns
Sellers worry that buyers with minimal down payments might struggle to close if appraisals come in low or if financial circumstances change. Addressing these concerns proactively strengthens your negotiating position regardless of loan type.
Strong pre-approval letters from reputable lenders, proof of reserves beyond down payment and closing costs, and shorter inspection timelines demonstrate commitment and capability. For first-time mortgage applicants, emphasizing stable employment at recognized employers like Amazon or Microsoft provides additional confidence.
VA and FHA offers sometimes face resistance due to property condition requirements and appraisal processes, but educated sellers in Bellevue and Redmond increasingly recognize these loans as reliable when backed by strong borrower profiles and experienced lenders who close on time.
Timeline and Process Expectations
Understanding typical timelines for loan approval and closing helps you plan your home search and make realistic commitments when you find the right property. Modern underwriting technology and experienced loan officers can expedite timelines significantly compared to industry averages.
From Pre-Approval to Closing
Pre-approval should occur before viewing homes, providing clarity on budget and demonstrating readiness to sellers. This process takes 24-48 hours with complete documentation and involves credit review, income verification, and preliminary underwriting.
Standard purchase timeline with best first home buyer loans:
- Day 1-2: Offer accepted, earnest money deposited, loan application submitted
- Day 3-5: Property appraisal ordered and scheduled
- Day 5-10: Initial underwriting review, document requests issued
- Day 10-15: Appraisal completed and reviewed
- Day 15-20: Final underwriting approval, clear to close issued
- Day 20-25: Closing documents prepared, final walkthrough completed
- Day 25-30: Closing meeting, funds disbursed, keys received
That timeline is typical across the industry. My team closes in 9 business days, which gives you a real edge when a seller is choosing between offers. Understanding home loan approval timeframes helps you negotiate realistic contract terms that protect your interests while meeting seller expectations.
Common Mistakes to Avoid
First-time buyers often make preventable errors that delay closing, reduce negotiating power, or result in less favorable loan terms. Awareness of these pitfalls improves outcomes significantly.
Financial Missteps During the Loan Process
Once you've applied for a mortgage, maintaining stable finances becomes critical. Large deposits, new credit accounts, job changes, and major purchases all trigger underwriting questions that can delay or derail approval.
Actions to avoid between application and closing:
- Changing employers or income structure
- Making large unexplained deposits
- Opening new credit cards or loans
- Making major purchases on credit
- Moving money between accounts without documentation
- Co-signing loans for others
Underwriters must verify that the financial picture at closing matches what they approved initially. Any changes require explanation and sometimes re-verification of employment and assets. For buyers using stock compensation or bonus income, maintaining consistency in employment and vesting schedules proves especially important.
Rate Shopping and Lender Selection
Not all lenders offering the best first home buyer loans deliver equivalent service, rates, or reliability. Strategic lender comparison protects your interests while ensuring smooth execution when timing matters.
Evaluating Total Costs vs. Interest Rates
The lowest advertised interest rate often comes with higher fees or points, making the total cost higher than alternatives with slightly higher rates but lower fees. The Annual Percentage Rate (APR) accounts for these factors but still doesn't capture all cost differences.
Request Loan Estimates from multiple lenders for identical scenarios, comparing not just interest rate but also origination fees, processing fees, underwriting fees, and required services. Some lenders mark up third-party services like title insurance and escrow, adding hundreds to total costs.
Credit Karma reviews top first-time homebuyer loans of 2026, comparing features that extend beyond rate to include customer service, technology platforms, and specialized programs for different buyer profiles.
For Seattle-area buyers, lender familiarity with local appraisal timelines, title company procedures, and market conditions impacts closing certainty. National online lenders sometimes struggle with regional nuances that local experts navigate seamlessly.
Property Type and Condition Requirements
Different loan programs impose varying requirements on property eligibility, affecting which homes you can purchase with each financing type. Understanding these limitations before falling in love with a property prevents disappointment and wasted time.
FHA and VA Property Standards
Government-backed loans require properties to meet specific safety and habitability standards verified during appraisal. Peeling paint, missing handrails, roof damage, and certain foundation issues can trigger repair requirements that sellers must address before closing or that reduce property eligibility.
These requirements exist to protect buyers from purchasing homes with immediate major repair needs, but they also limit options in neighborhoods where older housing stock predominates. In areas like Everett and Lynnwood with diverse housing ages, understanding which properties meet program standards helps focus your search appropriately.
Conventional loans generally impose fewer property requirements, accepting homes "as-is" more readily than government programs. For buyers interested in properties needing cosmetic updates or minor repairs, conventional financing often provides the only viable path even if the down payment requirement is slightly higher.
Post-Purchase Refinancing Strategy
Selecting your first mortgage should account for future refinancing opportunities that reduce costs or eliminate mortgage insurance. The best first home buyer loans position you for beneficial refinancing as your financial situation improves.
Planning Your Refinance Timeline
FHA borrowers paying permanent mortgage insurance should plan to refinance to conventional once they reach 20% equity and their credit score improves above 720. This transition eliminates the FHA monthly premium, which can add up to meaningful savings over the remaining loan term.
Conventional borrowers with PMI can request cancellation once the balance reaches 80% of the home's original value, and PMI ends automatically at 78%. Building equity quickly through additional principal payments or property appreciation accelerates this timeline substantially.
Market conditions permitting, monitoring opportunities to refinance into better terms maintains financial flexibility and reduces long-term housing costs. Setting calendar reminders to review options annually ensures you don't miss beneficial opportunities as rates fluctuate.
Local Market Considerations for Seattle Buyers
Seattle's unique market dynamics influence which loan programs deliver optimal results for different property types and neighborhoods. Understanding these local factors helps match financing to your specific homeownership goals.
Condo Financing and Warrantability
Seattle's substantial condominium inventory requires special attention to project approval status. Not all condo developments meet Fannie Mae, Freddie Mac, or FHA requirements, limiting available financing options.
Before making offers on condos in Bellevue or downtown Seattle, verify the project's approval status for your intended loan type. Working with knowledgeable mortgage professionals who maintain current information on approved projects saves time and prevents last-minute financing problems.
FHA-approved condos expand accessibility for buyers with minimal down payments, while non-warrantable condos require portfolio lenders willing to hold loans rather than selling them to secondary markets. These portfolio loans typically carry higher rates and stricter requirements.
Finding the best first home buyer loans in Seattle requires balancing down payment capacity, monthly budget, property type, and long-term financial strategy with current market conditions and qualification requirements. Whether you choose conventional financing for flexibility, FHA for accessibility, or VA for maximum benefits, matching your loan to your specific circumstances positions you for successful homeownership. Keith Akada brings 25+ years of experience helping Seattle-area first-time buyers navigate these complex decisions with clarity, transparency, and strategic guidance backed by specialized expertise in qualifying stock compensation for tech professionals. Discover how personalized mortgage guidance can maximize your buying power and simplify your path to homeownership at Mortgage Reel.
Related guides: 1st time home buyer programs in Seattle, Seattle down payment guide, conventional home loans, FHA home loans, VA home loans, and financing a home in Seattle.
Best First Home Buyer Loans in Seattle: FAQs
What is the best first home buyer loan in Seattle?
It depends on your profile. Conventional 3% down usually fits buyers with credit scores of 620 or higher and steady income, FHA fits scores from 580 or buyers who need more flexibility on debt, and VA is hard to beat for eligible veterans. WSHFC down payment assistance can pair with any of them.
How much do first-time buyers need to put down in Seattle?
Conventional loans allow as little as 3% down for qualified buyers, FHA 3.5%, and VA 0%. Plan separately for closing costs, which typically run 2% to 4% of the price once prepaid taxes and insurance are included.
What credit score do I need for a first-time buyer loan?
FHA allows scores as low as 580 with 3.5% down (500 with 10% down), and conventional loans generally start at 620. VA does not set a minimum score, but lenders do. Higher scores improve your pricing at every level.
Can my parents give me the down payment?
Yes. For a one-unit primary home, Fannie Mae allows the entire down payment to come from a gift at any down payment level, and FHA and VA allow gifts too. You will need a signed gift letter and a paper trail showing the transfer.
Do first-time buyers get a break on loan fees?
Often, yes. Fannie Mae and Freddie Mac waive certain upfront loan fees for first-time buyers earning up to $181,440 in King and Snohomish counties for 2026 (120% of area median income). HomeReady and Home Possible have a lower cap of $120,960. Eligibility depends on your full loan profile and is subject to credit approval.
Is FHA or conventional better for a first-time buyer?
FHA is more forgiving on credit and debt, but with less than 10% down its mortgage insurance lasts for the life of the loan. Conventional PMI can be removed later and conventional offers often look stronger to sellers, so buyers with a 620 or higher score usually compare both side by side.
Let's connect. Call or text (206) 601-3426, email keith@mortgagereel.com, or start your application. I will compare every loan you may qualify for, pressure-free.